According to IDC, worldwide server vendor revenue surged 52% year-over-year to a record $166.3 billion, as rising AI infrastructure spending, tighter component supply, and a rebound in shipment volumes combined to push prices and revenue to new highs.
The global server market posted its strongest quarter on record in the second quarter of 2026, according to IDC’s Worldwide Quarterly Server Tracker. Vendor revenue reached $166.3 billion, up 52.0% year-over-year and 35.7% sequentially, surpassing the previous high of $125.3 billion set only two quarters earlier, in the fourth quarter of 2025. AI infrastructure investment remained the dominant driver, but IDC’s data points to a market shifting on two fronts at once: shipment volumes are recovering even as prices keep climbing.
Worldwide unit shipments grew 15.4% year-over-year, IDC reported, alongside the 52.0% revenue increase. That combination marks a change from previous quarters, in which revenue gains were driven almost entirely by pricing and mix rather than volume. According to the research firm, buyers are now securing components and finished systems further in advance to guard against renewed price inflation and allocation risk, a pattern IDC likens to inventory buildup ahead of anticipated shortages rather than a shift in underlying demand.
Pricing tells its own story. Average selling prices for GPU-accelerated servers climbed from roughly $118,600 to nearly $170,200, a 43.6% year-over-year increase, even as GPU unit shipments fell 10.8%. In the non-accelerated segment, average prices rose from about $9,800 to nearly $13,000, up 33.5%, alongside a 16.7% increase in units. IDC attributes the increases primarily to DRAM and NAND flash pricing and continued component allocation, constraints the firm first flagged in the first quarter of 2026.
By platform, non-x86 servers generated $74.4 billion, up 146.0% year-over-year and now accounting for 44.8% of total market revenue, narrowing the gap with x86 systems. x86 server revenue reached $91.9 billion, up 16.1%. GPU-accelerated servers generated $87.4 billion, up 28.1%, representing 52.6% of total revenue, while other accelerated systems, based on FPGAs and ASICs, surged 237.6% to $27.5 billion.
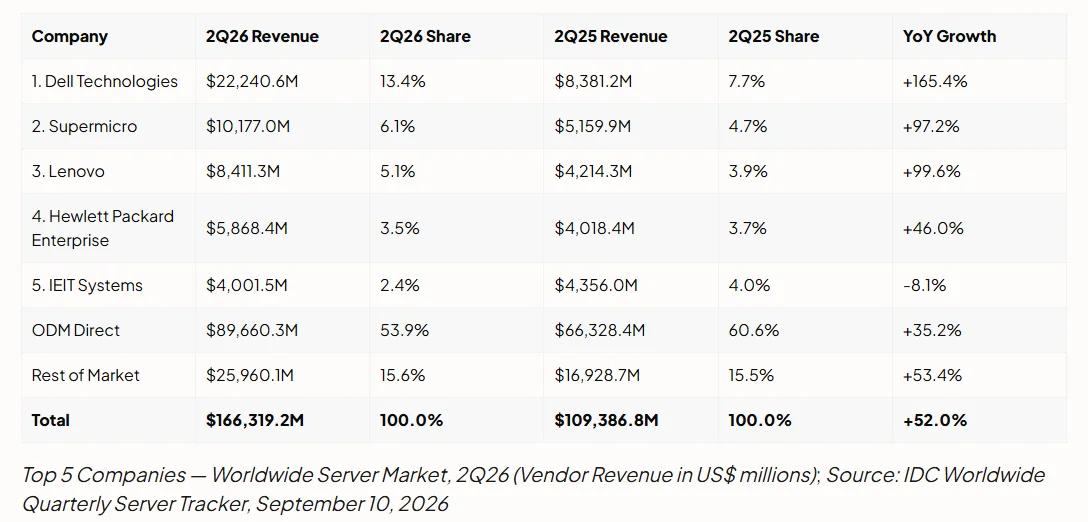
The competitive picture also shifted. Branded OEM vendors extended their gains against ODM Direct suppliers for a second straight quarter. Dell Technologies retained the top position with 13.4% revenue share, growing 165.4% year-over-year, the fastest pace among the top five vendors, which IDC attributed to record AI server orders. Supermicro held second place with 6.1% share and 97.2% growth, while Lenovo ranked third at 5.1% share, up 99.6%. Hewlett Packard Enterprise placed fourth with 3.5% share, up 46.0%, and IEIT Systems rounded out the top five with 2.4% share, down 8.1%. ODM Direct remained the largest single category by absolute revenue, at $89.7 billion, but its share of the market compressed from 60.6% in the second quarter of 2025 to 53.9% this quarter, as branded vendors captured a growing share of AI deployments.
Regionally, the United States remained dominant, generating $112.2 billion, or 67.4% of global revenue, up 54.9% year-over-year. China reached $26.4 billion, up 43.4%, a reacceleration from recent quarters. Western Europe grew 62.7% to $9.1 billion, and Central and Eastern Europe, though still a small base, grew 98.3% to $0.7 billion. Canada was again the fastest-growing region worldwide, up 202.6%, followed by the Middle East and Africa, up 68.8%, and Latin America, up 32.8%.
“The notable shift in the server market this quarter is in who is now buying,” said Kuba Stolarski, research vice president at IDC’s Computing Platforms and Service Provider Infrastructure group, according to the company. He noted that demand is broadening beyond the largest hyperscalers toward specialized cloud providers, sovereign AI programs backed by public capital, and enterprises adopting agentic and inferencing workloads, adding that power and facility readiness are becoming as binding a constraint as component supply.
For the channel, the growth in Western Europe and Central & Eastern Europe is notable even though both regions remain far smaller than the United States in absolute terms. Western Europe’s 62.7% year-over-year gain and Central & Eastern Europe’s 98.3% increase, albeit off a modest base of $0.7 billion, point to AI infrastructure spending broadening into markets where distributors, systems integrators, and managed service providers play a larger role than in hyperscaler-dominated regions. As branded OEM vendors such as Dell, Lenovo, and Hewlett Packard Enterprise keep gaining share against direct-sale ODM suppliers, that shift is likely to filter down into partner programs, financing structures, and configuration complexity at the reseller level.
IDC’s outlook suggests the AI infrastructure buildout has not yet reached a ceiling. With demand increasingly committed well in advance and capacity constraints extending from chips and memory to power and data center readiness, the coming quarters may hinge less on appetite for AI infrastructure than on the industry’s ability to actually deliver it. IDC’s Worldwide Quarterly Server Tracker defines a server as a multiuser computing device that delivers services over a network, distinguishing GPU-accelerated systems from those using FPGAs or ASICs and from non-accelerated machines, a taxonomy that underpins the vendor and platform comparisons in this report.
Dr. Jakob Jung is Editor-in-Chief of Security Storage and Channel Germany. He has been working in IT journalism for more than 20 years. His career includes Computer Reseller News, Heise Resale, Informationweek, Techtarget (storage and data center) and ChannelBiz. He also freelances for numerous IT publications, including Computerwoche, Channelpartner, IT-Business, Storage-Insider and ZDnet. His main topics are channel, storage, security, data center, ERP and CRM.
Contact via Mail: jakob.jung@security-storage-und-channel-germany.de